


This article originally appeared on FT Adviser.
An important shift in the application of AI is underway, and it will reshape both the financial advice and wider services sector. For the past few decades, software has been sold into services businesses to support their work. Whilst these tools have been useful, they have remained peripheral to the work itself.
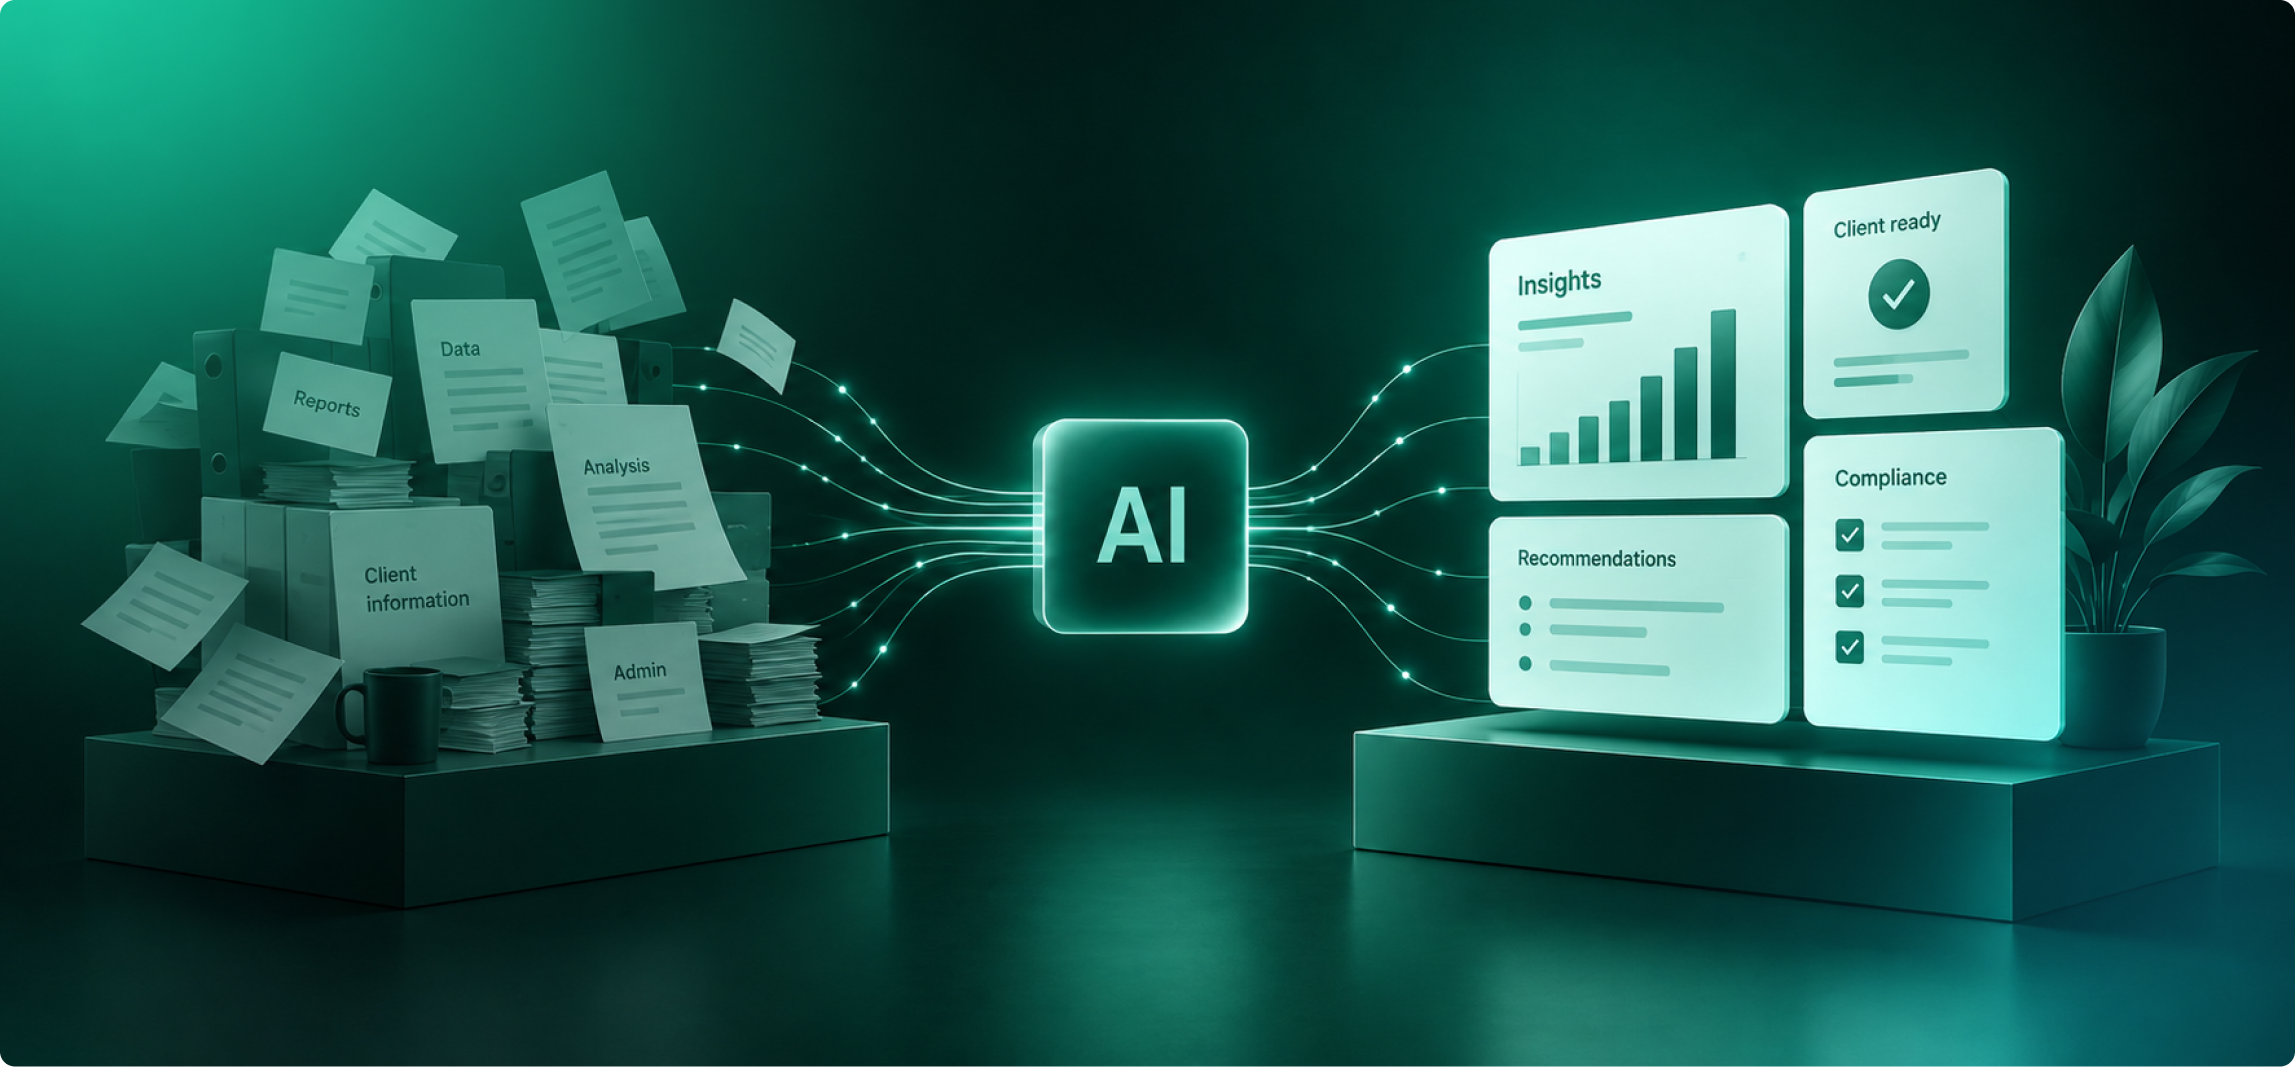
Today, we are seeing an emerging thesis and reality unfold in which the real prize will go to those who use AI not merely to support the work, but to actually do the work itself. The logic is simple: in large service markets like financial advice, the time and labour cost of doing the work are far greater than the cost of the tooling that supports it. Businesses do not use software for its own sake, they use software to achieve an outcome. Therefore, the value-capture opportunity is much larger if the application of AI can automate the production of the outcome itself.
The context today in financial advice
The FCA now estimates around 23 million consumers are underserved by the markets for advice and guidance, while fewer than one in ten people receive regulated financial advice on investments, pensions or retirement planning. Indeed, the regulator’s own 2025 research suggests regulated advice is associated with up to a 10% increase in wealth in the years following advice, although it notes that this association weakens over time. In any case, the implication is clear: making good advice more scalable, more consistent and more accessible will enable more people to achieve their financial goals.
In practice, every advice firm must onboard clients, collect and validate data, assess needs and risk, prepare suitability and compliance evidence, manage reviews, respond to life events, and provide day-to-day client servicing. Much of that operating layer, including the software supporting it and the data flowing from it, is fragmented, manual and expensive. In fact, it largely follows a process built around pen-and-paper.
However, despite these limitations, we are seeing AI used as a productivity add-on or ‘copilot’ to the current advice process. The copilot puts AI in the hands of the adviser, the adviser is the user of the tool, the tool makes them more productive, and they take responsibility for the output.
The impact of using AI as a copilot is two-fold. First, margins improve when firms reduce rekeying, chasing, file preparation, exception handling and after-the-fact compliance remediation. Secondly, client experience improves when onboarding is faster, communications are clearer and service becomes more proactive and personalised. In other words, the same capabilities that make a firm more efficient can also make it more valuable to the client, and enable it to serve more clients.
This productivity gain is real. However, it is mostly optimising a process that was never designed for an AI-native operating model, and it does not unlock the much larger opportunity – using AI to upgrade the operating model entirely and create genuine operating leverage through automation and agents.
The opportunity for financial advice
The next category-defining company in financial advice will not simply use a copilot to support advisers; it will use an ‘autopilot’ to actually do the work of advice itself, with appropriate human oversight and client servicing. To be clear, the adviser relationship is not what autopilots and automation should displace; the adviser relationship is what automation and everything else exists to protect.
What does this look like for the client? Less of what they never valued, such as repeating information they have already provided, waiting weeks for a recommendation, chasing an update, or receiving a review that arrives because the calendar says so rather than because anything has changed. And more of what they do value, including advice at the point a decision needs making, proactive support and guidance tailored to their personal circumstances, and reassurance that their interests are being looked after in the background. The autopilot will also dramatically reduce the cost for delivering advice and therefore increase the number of people that can access it.
How is this achieved? Put simply, context, data and the technical expertise to apply them. Human judgement becomes process. Process becomes data. Data becomes automation. This is how autopilots improve, how copilots and autopilots converge, and how advisers and clients will benefit.
It follows that the most valuable data to support automation is not generic market data or fragmented, incomplete and out-of-date data that plagues legacy technology stacks. It is contextualised AI-grade data, cleansed and produced across firm, adviser and client domains, like we see at Rimbal, including firm workflows, the client journey, file standards, the compliance framework, the service agreement, the regulator’s expectations and so on. As the systems accumulate more evidence of what good judgement looks like, they will push forward the frontier of automation and best-practice financial advice, and this will lower costs, increase accessibility and improve personalisation.
The future of financial advice
The winners applying AI will not be the organisations with the loudest tooling claims. They will be the firms that redesign service delivery around AI-grade data, accountable automation, agents and human judgement.
At Rimbal, we are building the operating system and intelligent infrastructure to enable independent financial advice firms to deliver better client outcomes, now and into the future. The opportunity is much bigger than enabling firm efficiency. It is the chance to define a new operating standard for advice, where the adviser remains central, but the framework supporting the advice process becomes faster, smarter, more automated and far more scalable.
In financial advice, that is a powerful combination: better margins for firms, better outcomes for more clients and a bigger addressable market for delivering both.


 Resources
